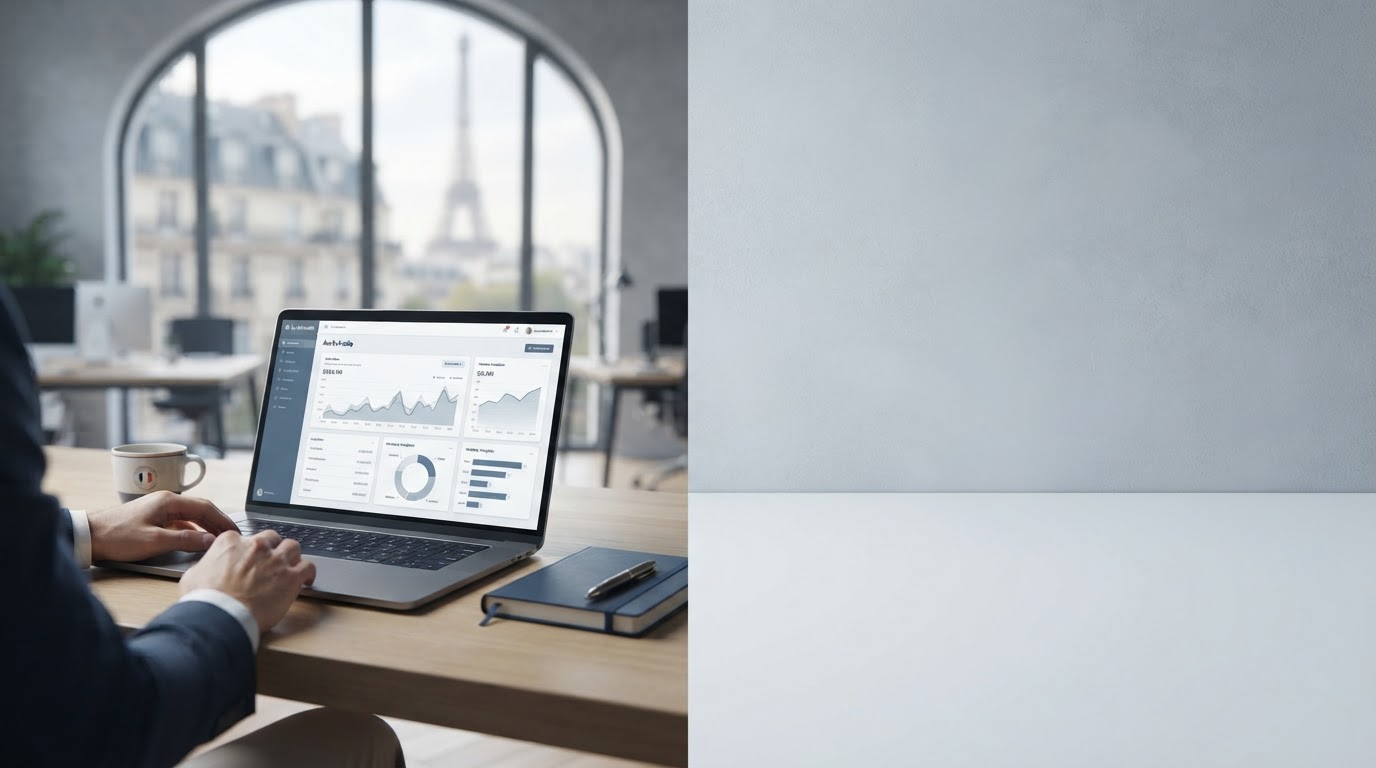
Aurévinelle continuously analyzes large volumes of market data to adjust the risk exposure of automated portfolios, without being dependent on a fixed office or time zone.
Overview of the monitoring interface: allocation by asset class, risk indicators and rebalancing history, viewable from a browser.
Each recommendation produced by Aurévinelle results from a reproducible process, documented and audited internally before being put into production.
Market flows, macroeconomic indicators and volatility data are continuously collected, normalized and then structured for model training.
Statistical and machine learning models estimate return scenarios and identify unstable correlations between asset classes.
Allocations are adjusted according to a defined return objective and a tolerated risk threshold, with rebalancing triggered automatically.
The entire processing flow — from ingestion to recommendation — is logged, allowing the origin of each portfolio adjustment to be traced during an audit.
Designed for users who frequently change workplaces, without guaranteed access to a fixed workstation or a stable connection all day long.
Positions are monitored on the main world markets, with aggregation of significant movements in a single summary table.
When the allocation deviates from the set thresholds, the system proposes or executes a rebalancing according to the delegation mode chosen by the user.
All portfolios and reports remain accessible from a browser, without local installation or dependence on a single workstation.
Before deployment, each strategy is compared with past market data in order to evaluate its behavior in different volatility regimes.
The graph opposite illustrates the trajectory of a typical strategy compared to a standard benchmark index, over a five-year rolling window including at least one market correction phase.
The performance gaps are presented with their associated volatility, in order to avoid any isolated reading of the return alone.
Consult the backtesting methodology →Past performance, simulated or actual, does not guarantee future results. Any investment carries a risk of capital loss.
The platform adapts to the desired level of involvement, without modifying the rigor of the underlying decision-making process.
For a user on the move frequently, the portfolio is continuously monitored by the system, with notifications limited to deviations deemed significant rather than every market change.
The desired objective is operational peace of mind: fewer one-off decisions, more confidence in a framework defined in advance.
For a more active profile, Aurévinelle provides the quantitative elements necessary for the manual or semi-automated adjustment of positions, particularly during phases of high market dispersion.
The precision sought concerns the justification of each arbitration, documented and consultable a posteriori.
Integration with an existing account is done without prior data migration. Evaluation access is offered without any time commitment.
Access models